Kirk Stauss & the Stauss Realty Team, Okoboji, Iowa
Second Home Buying Services in the Iowa Great Lakes
Second home buying services start from one truth: a second home is a financial decision wearing a lifestyle disguise. We handle both halves: how it is financed, what it costs to hold, what it does to your taxes and your residency, and how the title should read when the family is in on it.
What a second home here really involves · U.S. Census ACS 2024, Fannie Mae, Tax Foundation
Overview
What are second home buying services in Okoboji, Iowa?
Buyer representation for a home you will own but not live in full time: matching the property to how you will actually use it, financing it correctly as a second home, understanding what it costs to hold, and settling the tax, residency and title questions before closing rather than after. Stauss Realty provides that across West Okoboji, Okoboji, Arnolds Park, Wahpeton, Orleans, Spirit Lake, Milford, Lake Park and the wider Iowa Great Lakes.
The Iowa Great Lakes are built for this. Census American Community Survey estimates put 4,808 of Dickinson County’s 14,206 housing units (about 34%) in the “vacant for seasonal, recreational or occasional use” category. Roughly one home in three here belongs to someone whose everyday life happens somewhere else. That is not a quirk of the market; it is the market, and it is why the paperwork around part-time ownership is better understood here than in places where second homes are unusual.
Where this page differs from our vacation home buying services: that page is about the use: which lake suits your summer, what to inspect on a seasonal cottage, how short-term rental rules work. This one is about the ownership: how lenders classify the property, what Iowa’s residency rules do when you keep a home in two states, which tax benefits a second home does not get, and how the deed should read if a sibling or an adult child is buying in with you. Most buyers need both conversations. They are genuinely different conversations.
The Market
What does the Okoboji second-home market actually look like?
The short answer: it is one of the Midwest’s defining part-time-ownership markets: about a third of the county’s housing stock is seasonal, and the price range runs from in-town cottages to lakefront estates.
The seasonal share is the number that tells the story. 4,808 seasonal, recreational or occasional-use units out of 14,206 total means Dickinson County has more homes than its year-round population can fill: 17,990 residents against 14,206 housing units. Those seasonal units are 89.7% of all vacant housing in the county, so “vacant” here overwhelmingly means “someone’s second home in February,” not distress.
For context on how unusual that is: NAR defines a vacation-home county as one where seasonal, occasional or recreational-use housing accounts for at least 20% of homes. Dickinson County’s ~34% is well clear of that line (a comparison we are drawing from the Census figures, not a designation NAR has published for this county).
Price-wise, the range is genuinely wide. Median owner-occupied value countywide is $270,700, with in-town markets like Spirit Lake around $215,100 and Milford around $218,400, while West Lake frontage trades in an entirely different bracket. There is no audited second-home-segment dataset for these lakes, so we price per property from current comparable sales rather than quoting a segment median that does not exist.
Sources: U.S. Census Bureau American Community Survey 2024 5-year estimates, table B25004, via Census Reporter (estimates carry margins of error; the seasonal-unit figure is ±271); National Association of REALTORS vacation-home county definition; Tax Foundation county property-tax data. The 20%-threshold comparison is ours, drawn from the Census figures. Market data moves.
What would this property actually cost you to hold?
Taxes without the homestead exemption, insurance for a home that sits empty, dock and seasonal upkeep: the real annual figure, per property.
What’s Included
What does second-home representation actually cover?
The short answer: five things: getting the financing classification right, building the true carrying cost, vetting a house that will sit empty, structuring the offer, and closing it with the title and tax questions already settled.
The classification conversation, first
Second home or investment property is not a label you pick; it is a set of conditions your lender will test. Fannie Mae’s second-home rules require a one-unit home you occupy part of the year, suitable for year-round occupancy, under your exclusive control, not a rental-first property. Getting this straight before you write an offer prevents a re-underwrite three weeks in.
The honest annual number
Property taxes at Dickinson County’s 0.78%, but without the homestead exemption a primary residence would get. Insurance appropriate to a home that sits unoccupied for stretches. Winterization, opening in spring, dock and hoist installation, removal and storage, and any condo association (HOA) dues. No one-size figure exists; we build it per property.
Vetting a house that will be empty
A part-time home fails differently. How the plumbing, heat and systems handle an unoccupied Iowa January; whether the shutoffs and drains are where they should be; the roof and the gutters you will not be there to watch; dock and hoist condition and permit status; and on a condo, the HOA’s budget, reserves and rules, which we request and deliver for you and your attorney to review.
An offer built for a part-time buyer
Priced on comparable closed sales, with contingencies that protect your earnest money while you are three states away, and a written what-conveys inventory, because second homes often trade with furnishings, kitchenware, dock sections and hoists, and memory is a poor substitute for a list.
A closing with the title and tax questions already answered
Iowa’s abstract-and-attorney title work (an attorney examines the abstract of title, the recorded history of the property’s ownership), the groundwater hazard statement, any time-of-transfer septic inspection, and a closing you can complete from wherever you live. Before that: how the deed should read if more than one household is buying in, and a clear-eyed look at what this purchase does to your residency picture, with your own tax professional, not instead of one.
Financing
How is a second home financed differently?
The short answer: more down, priced higher than a primary home, and only if the property and your use of it meet the lender’s second-home conditions; otherwise it finances as an investment property on stiffer terms.
| Factor | Second Home | Investment Property |
|---|---|---|
| Maximum LTV on a purchase | 90%, so at least 10% down (1-unit, fixed or adjustable) | 85%, so at least 15% down (1-unit) |
| Cash-out refinance cap | 75% LTV | Lower still, and priced accordingly |
| Occupancy requirement | You must occupy it for some portion of the year, with exclusive control over the property | No owner-occupancy requirement |
| Rental use | Permitted within the rules, but it cannot be a rental-first property, a timeshare, or under a management firm’s control of occupancy | Rental is the point; rental income may be used in qualifying |
| Property type | One-unit dwellings only, suitable for year-round occupancy | One to four units |
| Pricing | Above primary-residence pricing: GSE upfront fees for second homes were raised 1.125%-3.875% by LTV in a 2022 FHFA change | Higher again |
Sources: Fannie Mae Selling Guide B2-1.1-01, Occupancy Types; Fannie Mae Eligibility Matrix (August 5, 2026, incorporated by reference into the Selling Guide); FHFA news release, January 5, 2022; the fee figures are that announcement’s, and GSE pricing grids have been recalibrated since, so treat them as the durable point that second-home money costs more, not as today’s quote. Above the $832,750 conforming limit for a one-unit home in 2026, financing moves to jumbo or other nonconforming terms. Confirm current terms with your lender.
Not sure which lane your purchase falls into?
The difference between a second home and an investment property is decided by conditions, not intentions, and it changes your down payment, your rate and your paperwork.
Residency
Will a second home here make you an Iowa resident?
The short answer: not automatically, but Iowa decides residency by rules worth reading before you close, not after, because an Iowa resident is taxed on all income from everywhere.
Two ways to become an Iowa resident (Iowa Admin. Code r. 701-300.17(422))
What this means for you: there are two independent doors. You only have to walk through one.
The rule states that for Iowa individual income tax purposes an individual is a resident if (1) the individual maintains a permanent place of abode within the state, or (2) the individual is domiciled in the state. It goes on to provide that a person determined to be a resident is subject to Iowa income tax on all of their income for the year, whether earned inside Iowa or outside it. That last part is why this section exists: the question is not really about the house, it is about the rest of your income.
The 183-day abode presumption
What this means for you: keep a place here and spend more than half the year at it, and the presumption runs against you.
Establishing a permanent place of abode requires maintaining it long enough “to create a well-settled physical connection with a given locality,” weighed against four factors: time spent in the locality, the nature of the abode, your activities there, and your intentions about the length and nature of your stay. The rule then sets a rebuttable presumption that you maintain a permanent place of abode if you keep a place of abode in Iowa and spend more than 183 days of the tax year in the state. “Place of abode” expressly includes a condominium (relevant if the lake place is a condo).
The domicile presumption, and the traps inside it
What this means for you: you can be presumed domiciled in Iowa even if you are here well under 183 days.
Domicile is where you intend to reside permanently or indefinitely and to return whenever you are away; every person has one and only one. The rule sets a rebuttable presumption that you are domiciled in Iowa if you maintain a residence or place of abode here, even if you are in Iowa fewer than 183 days, and any one of the following is true: you claim a homestead credit or military tax exemption on an Iowa home; you are registered to vote in Iowa; you maintain an Iowa driver’s license; or you do not reside in an abode in any other state for more days of the year than you reside in Iowa.
The mirror-image presumption, that you are not domiciled in Iowa, requires all five: no Iowa homestead credit or military exemption, not registered to vote in Iowa, no Iowa driver’s license, fewer than 183 days in Iowa, and an abode outside Iowa where you reside at least 183 days. The rule also notes that being absent from Iowa for 183 days, or any other extended period, does not by itself show you have abandoned an Iowa domicile.
Where this collides with the homestead exemption
What this means for you: the two rules point in opposite directions, and you cannot have it both ways.
Iowa Code § 425.11 defines the homestead as the dwelling the owner is occupying as a home on July 1 of the claim year and occupies as a home for at least six months of that calendar year. Six months is essentially the same line as the 183-day residency presumption. So: occupy the lake home little enough to stay comfortably a nonresident and you cannot claim the homestead exemption on it, and claiming that exemption is itself one of the domicile presumption’s triggers. There is no clever position here, only a decision about which state you intend to be home, made deliberately and in advance.
Sources: Iowa Administrative Code r. 701-300.17(422), resident determination (domicile precedent: Julson v. Julson, 255 Iowa 301, 122 N.W.2d 329, 331 (1963)); Iowa Code § 425.11, homestead definitions. These are rebuttable presumptions that turn on individual facts, and this page is general information rather than tax advice; bring your own tax professional into the decision before you close, not after.
What It Costs
What does a second home cost to hold, and what do you give up?
The short answer: the low property-tax rate helps, but you forgo the homestead exemption and the federal home-sale exclusion, and a part-time house has costs a full-time one does not.
| Item | How It Works | What To Plan For |
|---|---|---|
| Property tax | Dickinson County’s effective rate of 0.78% is tied for the lowest in Iowa, roughly half the 1.40% statewide rate | A genuine advantage; verify the current levy for the specific parcel with the county before closing |
| Homestead exemption | Requires occupancy as a home on July 1 and for at least six months of the calendar year (§ 425.11) | A second home does not qualify. Budget the tax without it |
| Insurance | A dwelling unoccupied for long stretches is a different risk from a full-time residence | Tell your carrier plainly how the home will be used and ask how the policy treats extended vacancy, before you rely on a quote |
| Seasonal work | Winterizing in autumn, opening in spring, dock and hoist installation, removal and storage | Recurring, predictable, and easy to underestimate. Get local pricing during due diligence |
| Someone to look in | Nine months of light use means nobody notices a failure until it is expensive | Decide who checks the property after storms and hard freezes, and what that arrangement costs |
| HOA dues | On a condo or an amenity community, dues and any special assessments | Review the budget, reserves and dues history during due diligence, not after closing |
Sources: Tax Foundation county property-tax data; Iowa Code § 425.11. The insurance line is a question to ask your own carrier rather than a claim about any policy; terms vary by insurer and by property.
Title & Family
How should the deed read if family is buying in together?
The short answer: Iowa’s default is tenancy in common, which is probably not what a family intends, so the wording has to be chosen at closing, not assumed.
| Form | When Iowa Applies It | What Happens On A Death |
|---|---|---|
| Tenancy in common | The default. A conveyance to two or more grantees each in their own right creates it, unless a contrary intent is expressed in the instrument | The deceased owner’s share passes through their estate to their heirs or devisees, which is how a lake place ends up shared among cousins |
| Joint tenancy with rights of survivorship | Presumed where the instrument identifies two grantees as married to each other, uses “joint tenants” or “joint tenancy” or words of similar import, or says “or their survivor” | The share passes to the surviving joint tenant |
| After a divorce decree | An annulment, dissolution or separate-maintenance order under § 598.21 operates as a muniment of title | It severs a joint tenancy and creates a tenancy in common in equal shares, unless the order provides otherwise |
Source: Iowa Code § 557.15, common forms of co-ownership of real property (as amended by 2014 Acts, ch. 1054, applying to instruments executed on or after January 1, 2015). General information, not legal advice; the deed should be drafted by an Iowa real estate attorney who knows your family’s intentions.
When You Sell
What happens to the tax picture when you sell?
The short answer: the federal home-sale exclusion generally will not cover a second home, and moving into it later helps but does not erase the years it was not your principal residence.
The exclusion a second home does not get (IRS Topic No. 701)
What this means for you: the $250,000 / $500,000 shelter is for principal residences.
To exclude gain you must meet both tests: you or your spouse owned the home for at least 24 months of the last five years, and you used it as a residence for at least 24 months of the previous five. Meeting both allows exclusion of up to $250,000 of gain, or $500,000 on a joint return. A home you visit but do not live in fails the use test. Separately, you generally cannot use the exclusion if you excluded gain on another home sale within the prior two years.
Converting it to your primary home later (§ 121(b)(5))
What this means for you: retiring to the lake house is a real plan, but the earlier years still count against the exclusion.
Periods after 2008 during which the property was not your principal residence are generally treated as nonqualified use, and gain allocable to those periods cannot be excluded, even once you move in and satisfy the two-year use test. One helpful exception: time between your last use of it as a principal residence and the sale is generally not counted as nonqualified use. Any depreciation allowed or allowable after May 6, 1997 is also recaptured and cannot be excluded. The worksheets are in IRS Publication 523.
Iowa’s transfer tax on the way out
What this means for you: a predictable, modest part of your closing costs.
Iowa’s real estate transfer tax runs $0.80 per $500 of price above the first exempt $500, under Iowa Code chapter 428A. Your closing statement will show it. Iowa also closes on the abstract-and-attorney system rather than conventional title insurance, which your closing team handles.
Sources: IRS Topic No. 701, Sale of your home; IRS Publication 523, Selling Your Home (section 121(b)(5) nonqualified use); Iowa Code chapter 428A. General information, not tax advice; run your own figures with a tax professional, because the allocation math depends entirely on your ownership timeline.
Representation, Compared
What does having your own agent change on a second-home purchase?
The short answer: five things: how the loan is classified, how the annual cost is built, how an empty house is vetted, how the title is worded, and whether the residency question gets raised before closing or after.
| Factor | On Your Own | With Stauss Realty |
|---|---|---|
| Loan classification | Discovered at underwriting, sometimes weeks in | Tested against Fannie Mae’s second-home conditions before you write the offer |
| Annual carrying cost | Principal, interest and a guess | Built per property: tax without the homestead exemption, insurance, seasonal work, docks, dues, oversight |
| Vetting | A standard single-family inspection checklist | The part-time-ownership items: winterization, freeze history, shutoffs, docks and permits, with HOA documents gathered for your review |
| Title wording | Whatever the default produces | Raised before closing when more than one household is buying in, and referred to an Iowa attorney to draft |
| Residency and tax | Researched afterwards, if at all | Flagged early, in plain language, with your own tax professional brought in before you commit |
How We Work
How do we run a second-home purchase?
The short answer: in three phases: settle the ownership questions, find and vet the property, then negotiate and close it remotely if that is easier for you.
Settle the ownership questions
The decisions that shape everything else, made before anyone tours anything.
- How you will really use it: weeks per year, which seasons, who else
- Second home or investment property, tested against the lender’s conditions
- The residency picture, raised early and referred to your tax professional
- Written buyer agreement: services and compensation on paper up front
Find it, and vet it properly
The right property, checked the way a part-time home needs checking.
- Lakes, towns and price bands matched to your actual use
- Showings in person or by video from wherever you live
- Winterization, freeze history, shutoffs, roof, docks and hoist permits
- HOA budget, reserves and rules requested and delivered for your review where they apply
Negotiate & close
Priced on evidence, closed without you moving your life around it.
- Offer priced on comparable closed sales, with protective contingencies
- A written what-conveys inventory: furnishings, dock sections, hoist
- Title wording settled with your attorney before the deed is drawn
- Abstract, attorney title opinion and a closing you can complete remotely
Why Stauss Realty
Why work with a local agent on a second home?
The short answer: because part-time ownership is the normal case here, and the questions it raises (classification, carrying cost, winterization, title, residency) are ones we answer every season.
The team’s background and approach are detailed on the About Stauss Realty page, with client words on the testimonials page. Nothing here promises a specific outcome, and nothing here is tax or legal advice.
About Kirk Stauss
Who is Kirk Stauss, and how does he help second-home buyers?
The short answer: Kirk Stauss is the broker and founder of Stauss Realty, with an office in Okoboji, and he has helped people buy and sell on the Iowa Great Lakes for nearly 30 years. For a second home, that means a local team running the purchase while you live somewhere else, and raising the financing, carrying-cost, residency and title questions before closing instead of after.
Who does Kirk help with second home purchases?
Buyers whose everyday life happens somewhere else, which here is about one home in three.
- Families keeping a primary home in another state and adding a place on the lakes
- Buyers deciding whether a purchase is a second home or an investment property before they talk to a lender
- Siblings, parents and adult children buying a lake place together
- Couples who plan to retire to the lake house someday and want the tax picture understood early
- Condo buyers who want a lock-and-leave place for weekends and summers
What second home problems does Kirk solve?
The ones that show up when part-time ownership is treated like a full-time purchase.
- A loan re-underwritten weeks in because the property never met the lender’s second-home conditions
- An annual budget that left out the missing homestead exemption, seasonal dock and hoist work, or HOA dues
- A house that sits empty through an Iowa January with nobody checking the shutoffs, drains and roof
- Deed wording left to Iowa’s tenancy-in-common default when family is buying in together
- A residency question discovered after closing instead of taken to your tax professional before it
Why work with Kirk Stauss on a second home?
Local presence for owners who are not here most of the year.
- Nearly 30 years helping people buy and sell on the Iowa Great Lakes
- An office in Okoboji and a team of lifelong locals who can be at the property when you can’t
- 9 Iowa Great Lakes communities served, from West Okoboji and Arnolds Park to Spirit Lake and Milford
- A 4.9-star Google rating, verified September 2026
Where
What does a second home here look like the rest of the year?
Not the July photographs: the seasons that decide what a part-time home actually asks of you.
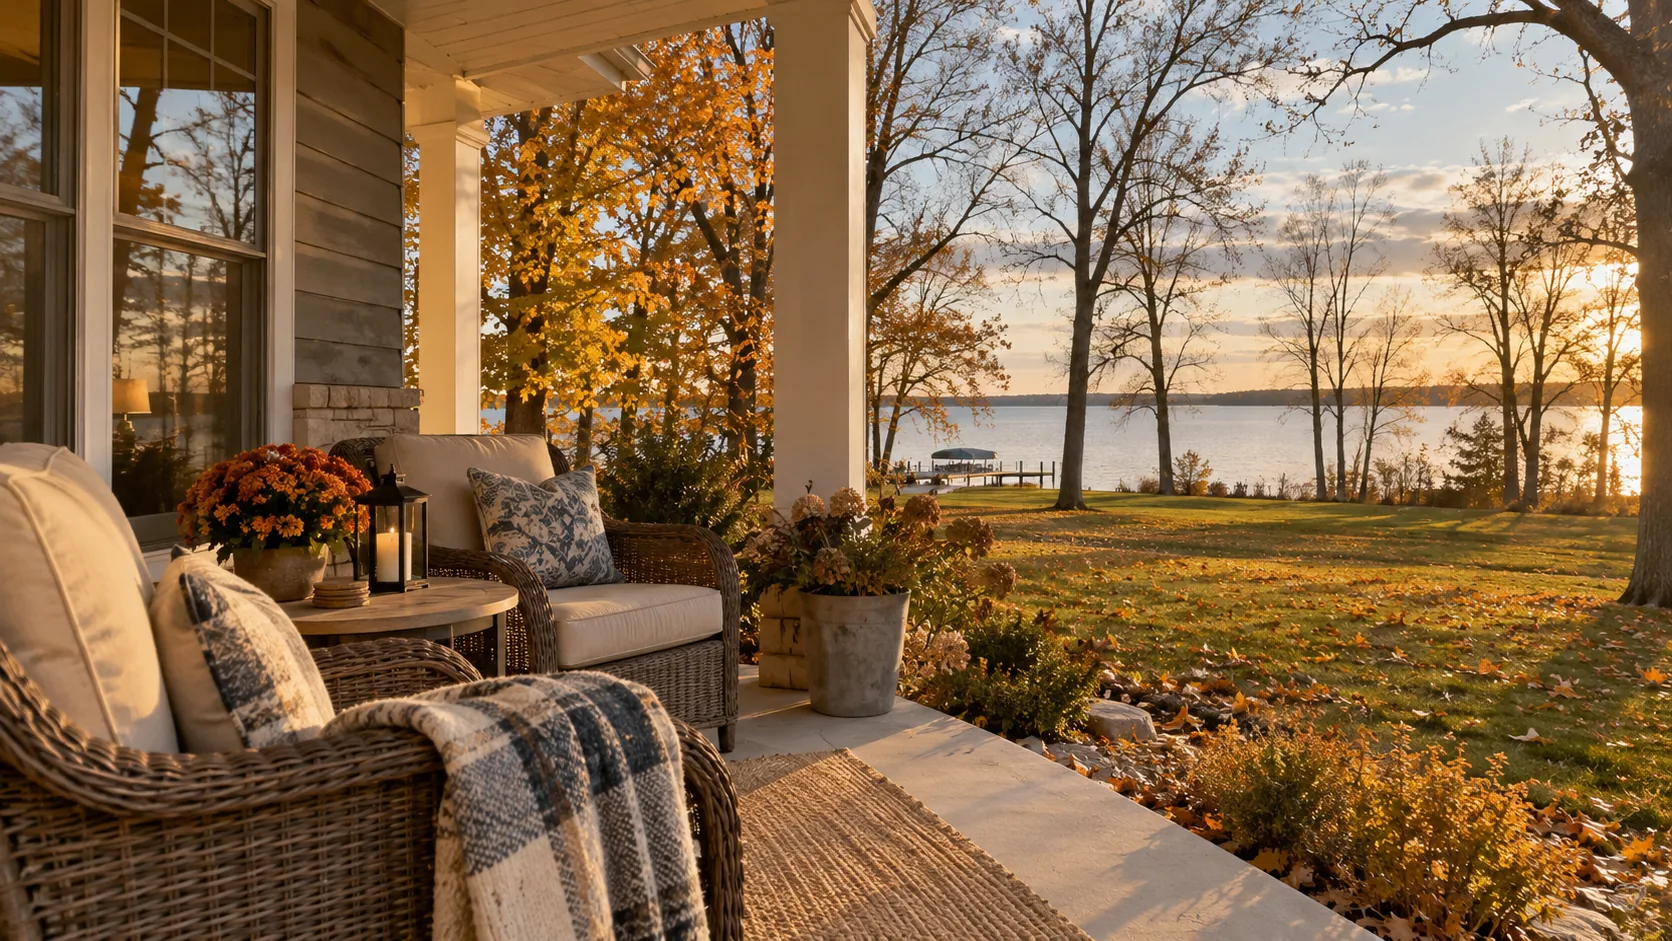
The porch in October
The season most second-home buyers never see before they buy, and the one that decides what the place really costs to keep.
Questions
What do second-home buyers ask most?
The short answer: full buyer representation for a home you will own but not live in full time: matching the property to how you will actually use it, getting the lender’s second-home classification right, building the true annual carrying cost, vetting a house that will sit empty for months, negotiating with a written what-conveys inventory, and closing with the title and residency questions settled rather than discovered afterwards.
The short answer: not automatically, but Iowa’s rules are worth understanding before you close, because an Iowa “resident” is taxed on all income, not just Iowa income. Under Iowa Admin. Code r. 701-300.17(422), you are a resident if you maintain a permanent place of abode in Iowa or are domiciled here. There is a rebuttable presumption of a permanent place of abode if you keep a place here and spend more than 183 days of the tax year in Iowa. Separately, there is a rebuttable presumption of Iowa domicile if you keep an abode here (even under 183 days) and also claim an Iowa homestead credit, or register to vote here, or hold an Iowa driver’s license, or spend more days here than in any other state’s abode. These are rebuttable presumptions turning on your facts. General information, not tax advice; work it through with your own tax professional before closing.
The short answer: occupancy and control, and your lender decides it by conditions rather than by what you call it. Fannie Mae’s second-home rules require a one-unit dwelling you occupy for some portion of the year, suitable for year-round occupancy, under your exclusive control, not a rental-first property, not a timeshare, and not subject to an agreement giving a management firm control over occupancy. Rental income is permitted inside those limits. A property bought primarily to rent finances as an investment property instead: 85% maximum LTV on a one-unit purchase rather than 90%, and higher pricing. See our investment property services if income is the point.
The short answer: at least 10% on a conventional second-home purchase. Fannie Mae’s Eligibility Matrix caps a one-unit second-home purchase at 90% loan-to-value, against 85% for an investment property. A cash-out refinance on a second home caps at 75%. Above the 2026 conforming limit of $832,750 for a one-unit home, you are into jumbo or other nonconforming financing. Cash purchases are also common in this market. Confirm current terms with your lender.
The short answer: yes, second-home money is priced above primary-residence money. In January 2022 the FHFA announced upfront fee increases of 1.125% to 3.875%, tiered by loan-to-value, for second-home loans delivered to Fannie Mae and Freddie Mac, effective that April. GSE pricing grids have been recalibrated since, so treat those figures as the announcement’s rather than today’s quote; the durable point is that you should budget for a second home to cost more to finance than your primary residence, and get a current quote from your lender.
The short answer: no. Iowa Code § 425.11 defines the homestead as the dwelling house the owner, in good faith, is occupying as a home on July 1 of the claim year and occupies as a home for at least six months during that calendar year. An ordinary second home does not meet the six-month occupancy test, so it does not qualify, which means you budget Dickinson County’s 0.78% effective rate, tied for the lowest in Iowa, without that exemption. Note the tension worth thinking about: occupying the home enough to qualify is also enough to raise the residency questions above.
The short answer: the federal home-sale exclusion generally will not shelter it. IRS Topic No. 701 requires both an ownership test and a use test: owned at least 24 months of the last five years and used as a residence at least 24 months of the previous five, to exclude up to $250,000 of gain, or $500,000 filing jointly. A home you visit but do not live in fails the use test. Iowa’s transfer tax also applies on the sale at $0.80 per $500 of price above the first exempt $500. General information, not tax advice.
The short answer: it helps, but it does not wash the earlier years. Under section 121(b)(5), periods after 2008 during which the property was not your principal residence are generally “nonqualified use,” and gain allocable to those periods cannot be excluded even after you move in and satisfy the two-year use test. There is a useful exception: time between your last use of it as a principal residence and the sale is generally not counted as nonqualified use. Any depreciation allowed or allowable after May 6, 1997 is also recaptured. The mechanics are in IRS Publication 523; run your actual numbers with a tax professional. If the plan is to make the lake your full-time home, our relocation real estate services cover that move.
The short answer: yes, within the rules. Fannie Mae permits rental income on a second home provided the borrower does not use that income to qualify and every other second-home condition still holds: you occupy it part of the year, you keep exclusive control, and no management firm controls occupancy. Cross the line into a rental-first property and it is an investment property at underwriting. Iowa law is unusually permissive about short-term rentals themselves under Iowa Code § 414.1, but your condo HOA’s rules can still restrict them. Our vacation home services page covers the rental side in depth.
The short answer: there is no single figure, so we build it per property. The components are consistent: property taxes at Dickinson County’s 0.78% effective rate, tied for the lowest in Iowa, but without the homestead exemption; insurance appropriate to a dwelling that sits unoccupied for long stretches, which is worth asking your carrier about directly; winterizing in autumn and opening in spring; dock and hoist installation, removal and storage; any HOA dues; and someone to look in on it. We total the real number before you write an offer.
The short answer: decide it deliberately, because Iowa has a default and it may not be what you want. Under Iowa Code § 557.15, a conveyance to two or more grantees each in their own right creates a tenancy in common unless a contrary intent is expressed. Joint tenancy with rights of survivorship is presumed only where the instrument identifies two grantees as married to each other, or uses “joint tenants”/”joint tenancy” or words of similar import, or says “or their survivor.” The difference decides what happens to a share when an owner dies. We raise it before closing; an Iowa real estate attorney should draft it.
The short answer: it depends entirely on how the deed was written. A tenancy-in-common share passes through the deceased owner’s estate to their heirs or devisees, which is how a lake place ends up owned by cousins who barely know each other. A joint tenancy with rights of survivorship passes to the surviving joint tenant instead. Iowa Code § 557.15 also provides that an annulment, dissolution or separate-maintenance order under § 598.21 severs a joint tenancy and creates a tenancy in common in equal shares unless the order says otherwise. Families who intend a lake place to stay in the family should get this right at purchase, with an Iowa attorney. Not legal advice.
The short answer: yes, it is the normal case here rather than the exception. About a third of Dickinson County’s housing is seasonal or occasional-use, so remote purchasing is routine for local lenders, closers and inspectors. Video tours, electronic signatures and remote closings are standard, and your agent does the local legwork: showings, the home inspection, the dock and shoreline check, and the final walkthrough.
The short answer: the things that fail when nobody is watching. How the plumbing, heat and systems handle an unoccupied Iowa January, and whether shutoffs and drains are accessible and clearly marked; the roof, gutters and grading you will not be there to monitor; evidence of past freeze damage; dock and hoist condition and whether required Iowa DNR permits are current; and on a condo, the HOA’s budget, reserves and rules. A standard single-family checklist does not ask most of this.
The short answer: by the numbers it is one of the Midwest’s defining part-time-ownership markets. Census ACS 2024 estimates put 4,808 of Dickinson County’s 14,206 housing units (about 34%) in the seasonal, recreational or occasional-use category, comfortably above the 20% share NAR uses to define a vacation-home county (that comparison is ours, drawn from the Census data). Dickinson County also carries an effective property-tax rate of 0.78%, tied for Iowa’s lowest. Whether it suits you depends on travel time, how many weeks you will really use it, and the carrying cost, which is what the first conversation works through.
The short answer: Iowa homes sold in a median of 16 days statewide in July 2026 per the Iowa Association of REALTORS, so prepared buyers move decisively, and the lake market concentrates into the warm months. After acceptance, allow several weeks for financing, inspection and Iowa’s abstract-and-attorney title work. If you are shopping from out of state, have your mortgage pre-approval in hand before the summer trip that finds the house; that is the trip on which most of these decisions actually get made.
The short answer: choose for fluency in part-time ownership. Ask how they separate a second home from an investment property at underwriting; whether they can explain what the homestead exemption and the federal home-sale exclusion do and do not cover here; how they vet winterization, docks and association rules; and how they handle co-ownership and title wording when more than one household is buying in. Stauss Realty’s agents have spent their lives on these lakes and hold a 4.9-star Google rating.
In Summary
A second home on the Iowa Great Lakes is a normal thing to own here (about a third of Dickinson County’s housing is seasonal or occasional-use), but it is owned under different rules than the house you live in. Conventional second-home financing wants at least 10% down and is priced above primary-residence money, and it only applies if the property meets the lender’s occupancy conditions; otherwise it is an investment property. Dickinson County’s 0.78% effective property-tax rate is tied for the lowest in Iowa, but a second home does not get the homestead exemption, which requires occupancy on July 1 and for six months of the year. The federal home-sale exclusion generally will not shelter the gain, and moving in later does not erase the nonqualified-use years. Iowa’s residency rules deserve a look before closing rather than after, because an Iowa resident is taxed on all income. And if family is buying in, Iowa’s default is tenancy in common, so the deed wording is a decision, not a formality. Our job is to put all of that on the table early, build the real annual number, and close it cleanly from wherever you live.
Let’s Talk
Start with how you’d actually use it
Tell us how many weeks a year you’d really be here, which seasons, and who else is involved. You’ll get an honest read on what that costs to own, which lane it finances in, and the questions to take to your tax professional before you commit.
By proceeding, you consent to be contacted by Stauss Realty about real estate related matters by phone, email, or text at the contact details provided, but not as a condition of purchase. Message frequency varies; message and data rates may apply; reply Stop to cancel.